
Oil shock and AI-spending jitters test markets as rate hikes return to the agenda
This week at a glance
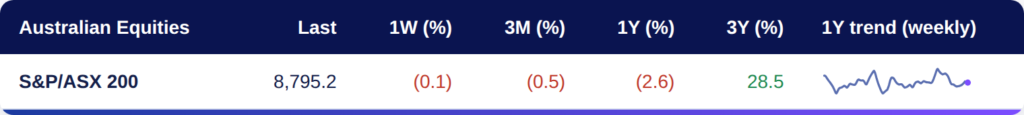
Oil and AI spending set the tone. Brent crude jumped to about US$117 a barrel, its highest level in months, after Houthi strikes on Saudi Arabia revived fears of a wider Middle East conflict. Meta lifted its 2026 capex guidance to US$135–145bn, reigniting AI-spend worries and sending the Nasdaq down 2.6% on Thursday. Investors rotated into defensives and bonds, with US 10-year yields falling 9 basis points to 5.00%. At home, Q3 CPI on 28 October will help decide whether the RBA lifts rates on 3 November, with markets pricing roughly a 60–65% chance. Markets expect the Fed to hold on 28 October but price a December hike.
Our view: Stay diversified, keep duration in high-quality bonds with yields near 5%, and use volatility in quality growth names rather than chasing energy after a sharp run.
Australia Market
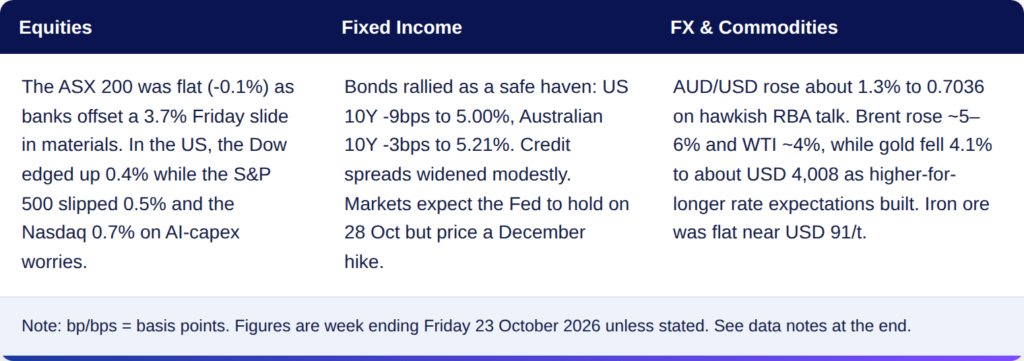
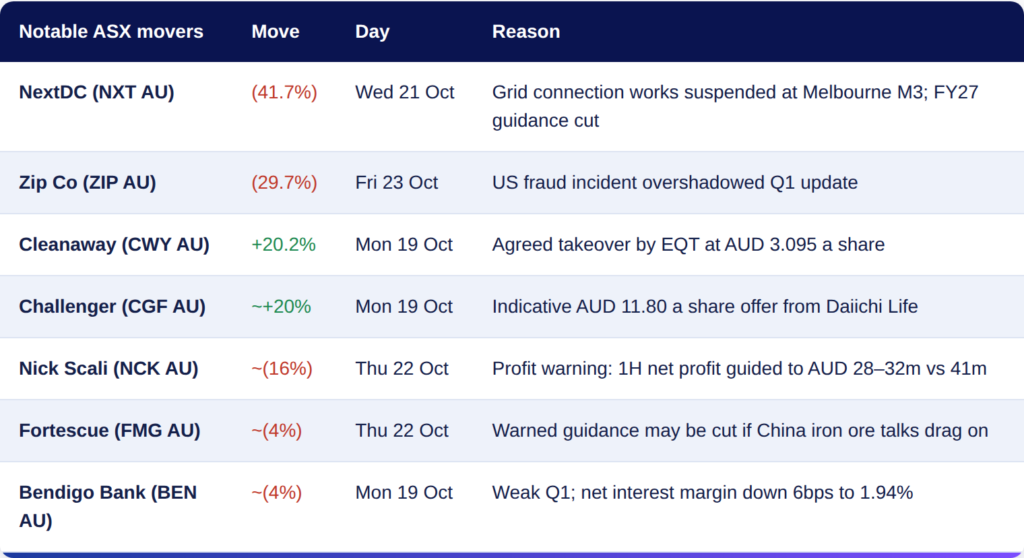
ASX: The S&P/ASX 200 closed Friday at 8,795.2, down about 0.1% for the week — its first weekly loss in four weeks. The index drifted lower from Wednesday’s 8,831 as hawkish RBA commentary lifted the odds of another rate rise. On Friday, banks rallied (Financials +1.7%) while Materials fell 3.7% as gold slid and BHP’s copper output disappointed.
Sectors: Defensive and rate-sensitive income sectors held up best, with Financials, Consumer Discretionary and Utilities leading on Friday. Materials was the clear laggard: a third lithium bear market in a decade (Pilbara Minerals, Liontown and Mineral Resources down 19–34% over a month), Fortescue’s guidance warning and gold’s 4% weekly fall all weighed.
Corporate activity: Takeover interest returned. EQT agreed to buy Cleanaway at AUD 3.095 a share (about AUD 9.3bn including debt), and Japan’s Daiichi Life made an indicative AUD 11.80 a share offer for Challenger, in which it already owns 20.4%.
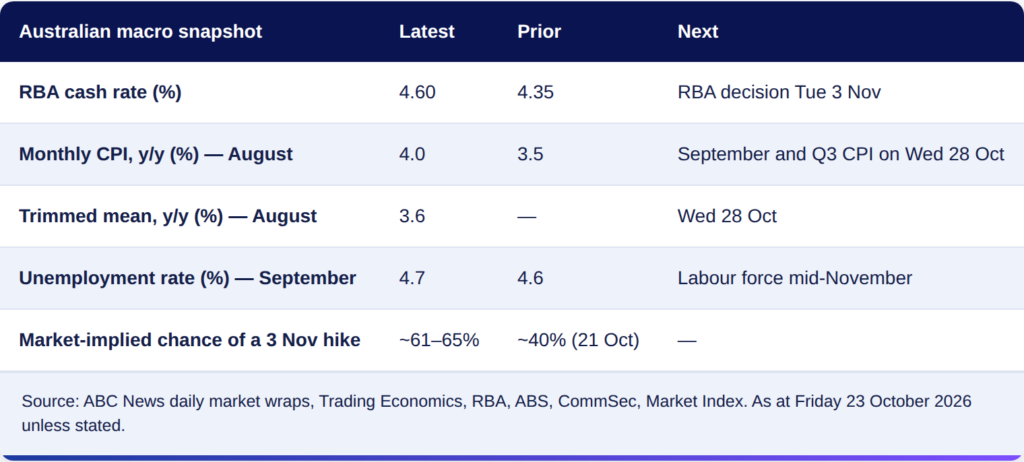
RBA & macro: The cash rate is 4.60% after four rises this year. Deputy Governor Hauser said on 21 October that the inflation outlook was worse than in August, with oil about a third above RBA assumptions. Markets now price roughly a 60–65% chance of a fifth hike on 3 November, and fully price one by February 2027. Flash October PMIs were weak, with services falling to 47.8 from 51.9, and Domain reported a record 4.7% fall in capital-city house prices in the September quarter.
US Market
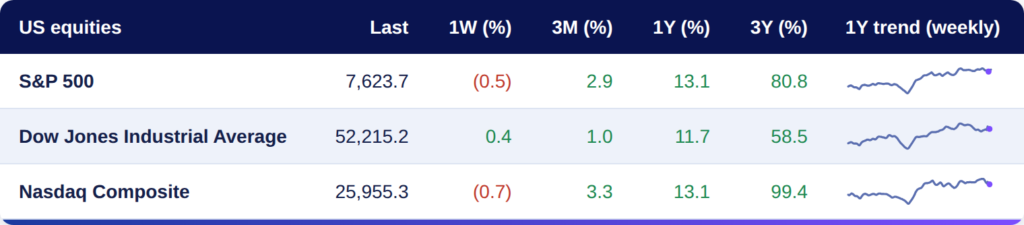
Indices: A choppy week ended mixed. The Dow rose 0.4% to 52,215 despite a 650-point fall on Friday, while the S&P 500 lost 0.5% to 7,624 and the Nasdaq fell 0.7% to 25,955. The S&P 500 is still up about 13% over the past year.
Drivers: Stocks rose through Wednesday after strong results from SpaceX and Super Micro, but Meta’s higher capex guidance sparked Thursday’s AI sell-off (S&P ‑1.2%, Nasdaq ‑2.6%). Friday’s oil spike on Middle East escalation added pressure.
Breadth & earnings: Under the surface, the average S&P 500 stock rose 1.1% while the Magnificent 7 fell 2.0% — a sign that money is rotating rather than leaving the market. Of the 24% of S&P companies that have reported Q3, 83% beat estimates, and blended earnings growth is running near 30%.
Fed: The FOMC decides on 28 October. Markets expect a hold at 3.75–4.00% but price a roughly 76–80% chance of a December hike, with September CPI at 3.7% y/y and oil adding to inflation risk.
Fixed Income
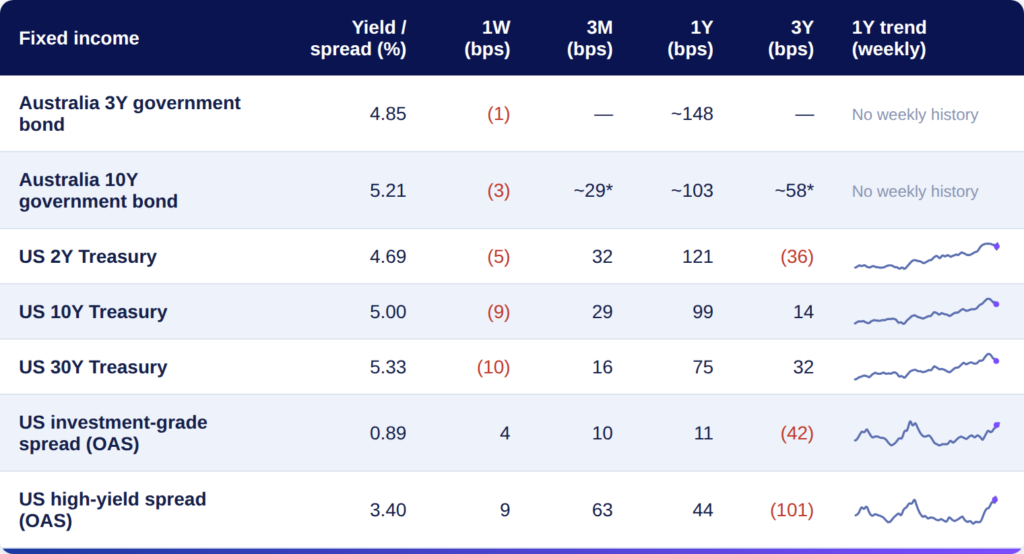
Australia: Australian government bond yields fell only modestly — 3Y to 4.85% and 10Y to 5.21% — lagging the US rally because hawkish RBA comments lifted near-term hike expectations. Australian 10Y yields are up about 1 percentage point over the past year, and the AU–US 10Y spread is about +21bps. This week’s Q3 CPI is the key risk for the front end.
US Treasuries: Yields rose early in the week (10Y peaked at 5.15% on Wednesday), then fell 17bps on Thursday — the biggest one-day drop in more than a year — as investors sought safety during the AI sell-off and Middle East escalation. Over the week the 2Y fell 5bps to 4.69%, the 10Y 9bps to 5.00% and the 30Y 10bps to 5.33%, flattening the curve.
Credit: US investment-grade spreads widened 4bps to 89bps and high-yield 9bps to 340bps, with most of the move on Thursday’s risk-off day. Spreads remain tight by historical standards, so we prefer quality over yield-chasing in high yield.
Our take: With US and Australian 10-year yields both above 5%, high-quality bonds again offer meaningful income and a buffer if growth slows. We would add duration gradually rather than all at once, given hike risk from the RBA and Fed.
FX & Commodities
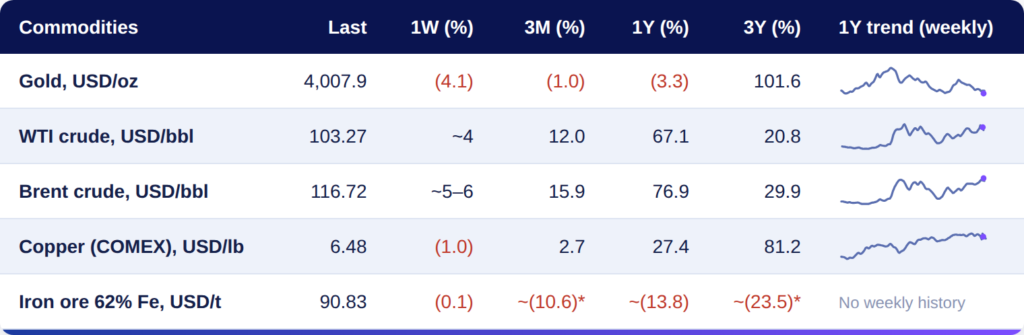
Energy: Oil surged on Friday after Houthi attacks on Saudi Arabia and expectations of renewed US strikes on Iran; Saudi Aramco reportedly told staff to evacuate its Dhahran headquarters. Front-month Brent closed near USD 117 a barrel, up roughly 5–6% on the week, and WTI rose about 4% to USD 103. US crude inventories fell 3.1m barrels, more than expected, and the US Energy Department announced a 315,000-barrel loan from its Northeast heating-oil reserve as heating-oil futures neared record levels.
Gold & metals: Gold fell 4.1% to about USD 4,008 an ounce, its lowest since mid-July, as hotter US inflation and the oil spike pushed out rate-cut hopes. Copper slipped 1% to a five-week low during the AI sell-off. Iron ore was steady at about USD 91 a tonne.
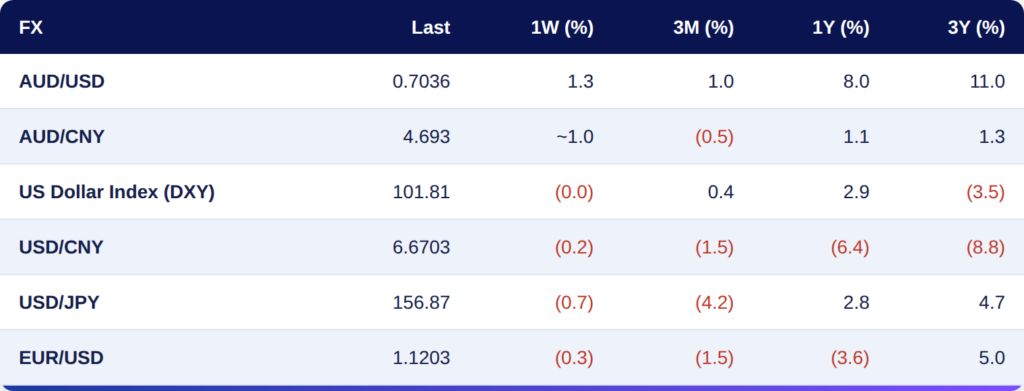
FX: The US Dollar Index was flat at 101.8. AUD/USD rose about 1.3% to 0.7036, near a five-week high, as hawkish RBA comments widened the expected rate gap with the Fed. That also lifted the AUD against the CNY by about 1%. The yen firmed 0.7% to 156.9 per US dollar on safe-haven demand.
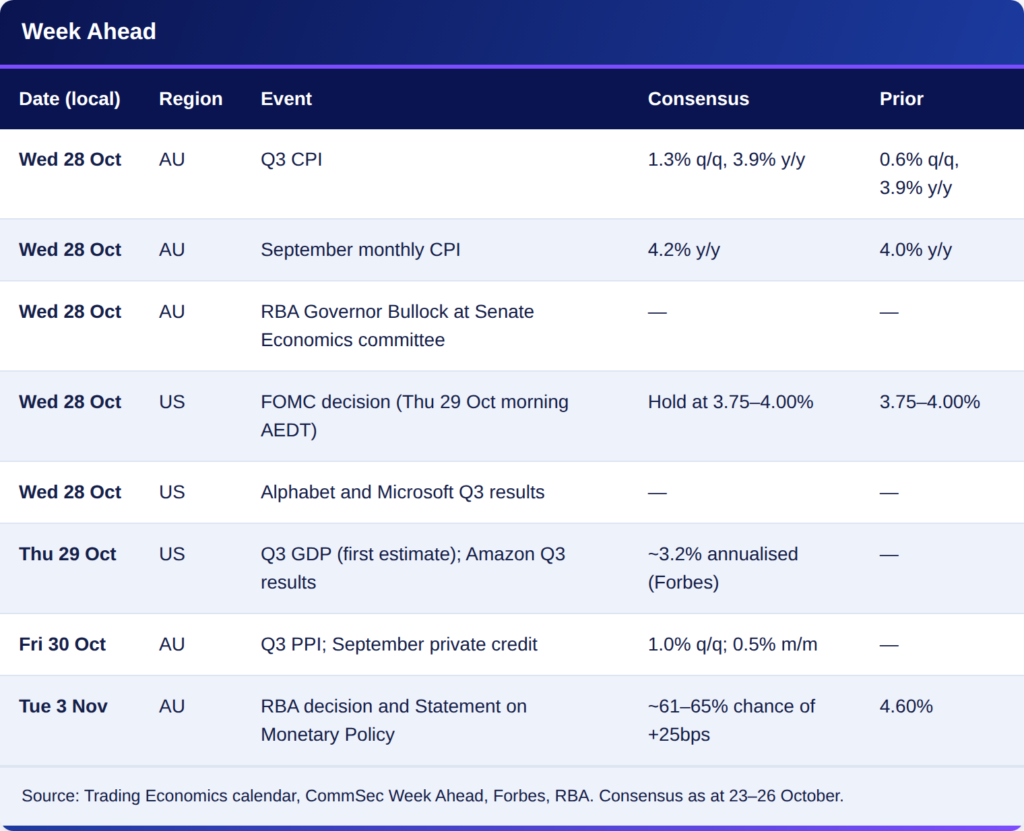
Also reporting this week: Boeing, Coca-Cola, UPS, Eli Lilly, Starbucks, Chevron and ExxonMobil, among 179 S&P 500 companies.
Questions about how this week’s moves could affect your portfolio? Speak with your BOA Private Wealth adviser.
This article is intended as general information only and does not constitute legal, financial or tax advice. Specific eligibility and the amount of any refundable tax offset should be determined based on the company’s individual circumstances and the applicable tax legislation.